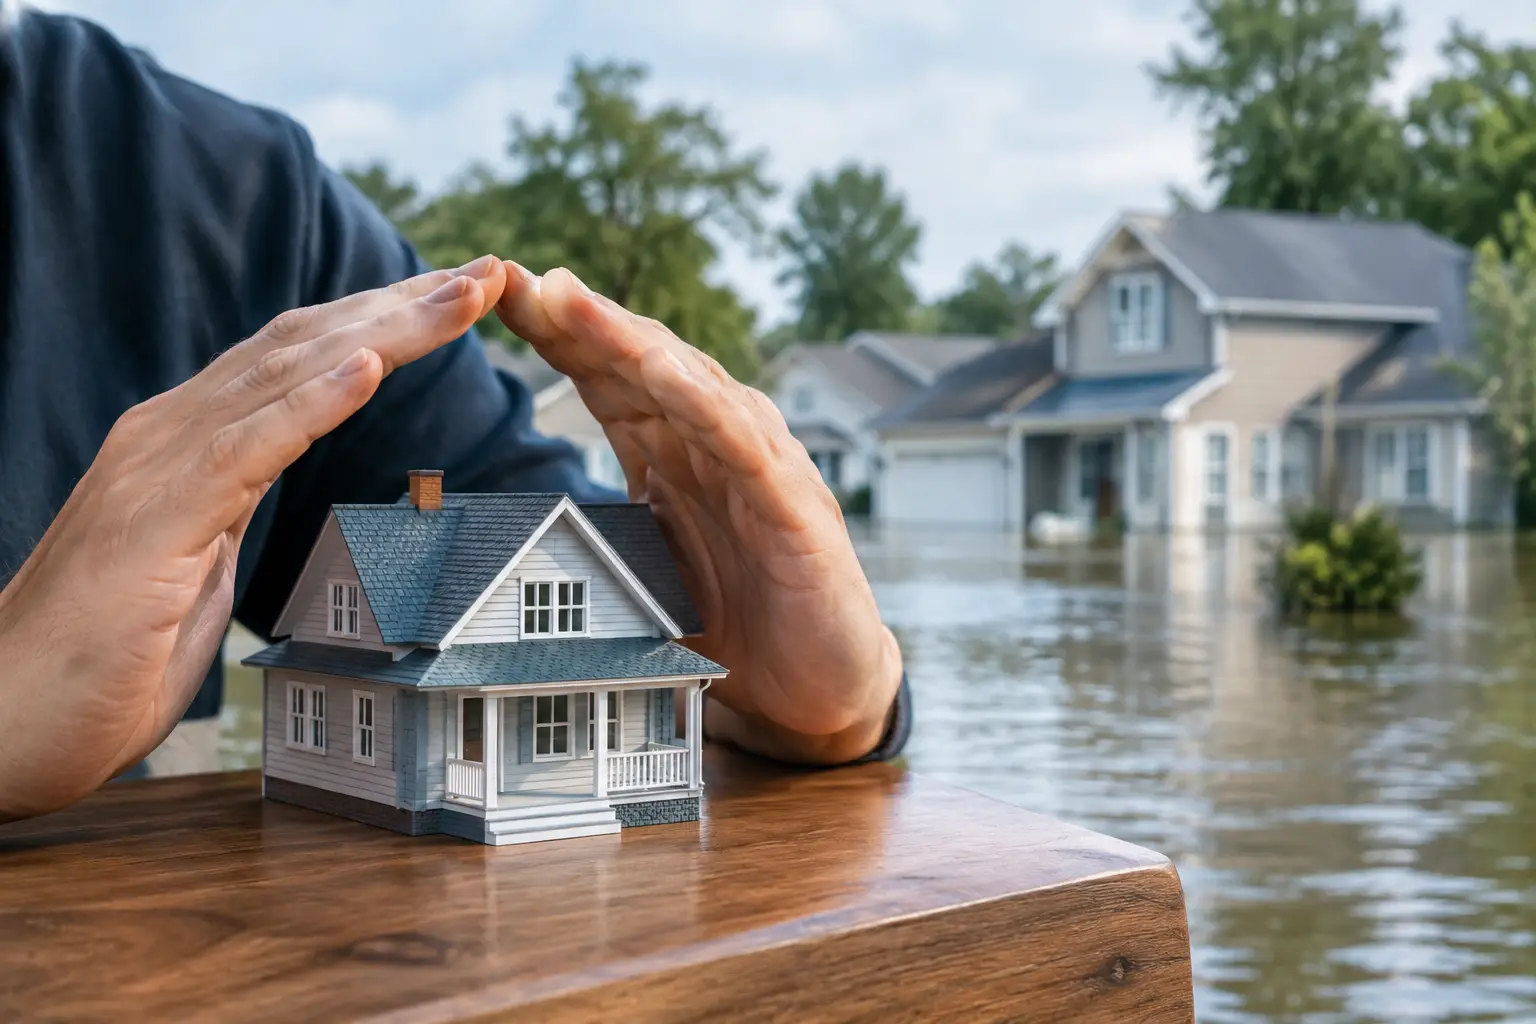
A storm can leave two neighboring homes with similar water damage and very different claim outcomes. The difference often comes down to where the water started. So, does homeowners insurance cover flooding? In most cases, no. A standard homeowners policy generally excludes flood damage, even when the water enters through a door, foundation, or damaged part of the home.
That answer can feel frustrating, especially for homeowners who reasonably assume their policy covers weather-related damage. But insurance policies separate water losses by cause. Knowing that distinction before a storm is far easier than learning it while filing a claim.
Does Homeowners Insurance Cover Flooding From Rain?
Usually, no. For insurance purposes, a flood typically means water that has covered land that is normally dry and affects two or more properties or two or more acres. Heavy rain that overwhelms a drainage system, runoff that enters a home, rising water from a creek, or storm surge from a hurricane can all fall under flood damage.
A standard homeowners policy may cover certain sudden and accidental water losses, but that is different from flooding. For example, coverage may apply when a supply line bursts inside the home and damages flooring or walls. It may also help with rain damage that enters through a roof that was first damaged by a covered wind event. The exact answer depends on the policy language, cause of loss, deductible, and any exclusions.
The source of the water matters more than how much damage it causes. Water that rises or flows in from outside is often a flood claim. Water that escapes from an appliance, pipe, or plumbing system may be a homeowners claim. When wind, rain, drainage, and plumbing are all involved, the facts can be more complicated, which is one reason prompt documentation matters.
What Standard Homeowners Insurance May Cover
Homeowners insurance is still a valuable part of protecting a home. While it usually excludes flood damage, it can cover many other losses, subject to policy terms and deductibles. Covered causes may include fire, theft, certain wind and hail damage, and some sudden water damage from inside the house.
Consider these common examples. If wind lifts shingles and rain damages the ceiling below, the homeowners policy may respond because wind created the opening. If a washing machine hose suddenly fails and water damages a room, that may also be covered. If a sewer backs up into the home, coverage is not always automatic, but an optional water backup endorsement may be available.
That endorsement is useful, but it is not flood insurance. Sewer or drain backup coverage addresses a different type of loss and typically has its own limit. A homeowner should not assume an endorsement for backup water will pay for damage caused by rising stormwater outside the property.
What Flood Insurance Can Protect
Flood insurance is designed for damage caused by flooding, including heavy rainfall, river overflow, coastal surge, and drainage-related water that enters a property from the ground level. Coverage can be obtained through the National Flood Insurance Program, often called the NFIP, or through certain private insurers.
A flood policy commonly separates protection into two parts: building coverage and contents coverage. Building coverage can help pay to repair the insured structure and certain permanently installed items, such as electrical systems, plumbing, furnaces, water heaters, and built-in appliances. Contents coverage can help protect personal belongings such as furniture, clothing, electronics, and other eligible possessions.
The details matter. In many cases, personal property is not automatically included with a flood policy unless contents coverage is selected. Basement coverage can also be limited. Items like finished walls, flooring, furniture, and valuables stored below ground level may receive limited or no coverage, depending on the policy and location of the items.
Flood insurance also may not provide the same additional living expense protection that homeowners expect from a standard homeowners policy. If a home becomes temporarily unlivable after a flood, ask specifically whether the policy includes help with temporary housing and related expenses. Private flood policies may offer broader options in some situations, but terms vary by carrier.
Who Needs Flood Coverage?
If a mortgage lender determines that a home is in a designated high-risk flood area, flood insurance may be required as a condition of the loan. But a lender requirement is not the same thing as a complete risk assessment.
Many flood losses occur outside the highest-risk mapped areas. A home can be far from the coast or a major river and still face flood exposure from intense rainfall, poor drainage, development that changes runoff patterns, or overwhelmed storm sewers. This is especially familiar to homeowners around Houston, Rosenberg, Richmond, and other Texas communities where severe rain can create problems quickly.
Flood maps are a helpful starting point, not a guarantee. They may not reflect every drainage issue near a property, recent construction, or future weather patterns. A practical review looks at the home’s location, elevation, prior water history, nearby channels and drainage, foundation type, and the cost to repair or replace the property after a serious water event.
How Much Flood Insurance Is Enough?
The right amount depends on what needs protection. Building coverage should be based on the cost to rebuild the home, not simply its market value or mortgage balance. Construction prices, materials, local labor costs, and updates to building codes can all affect that number.
Contents coverage should reflect what it would cost to replace belongings, not what they might sell for today. Walk through the home room by room and think beyond furniture. Clothing, kitchen items, tools, electronics, children’s belongings, and stored seasonal items can add up quickly.
Ask about deductibles as well. A higher deductible may lower the premium, but it also increases the amount the household pays out of pocket after a claim. Make sure the deductible is realistic during an already expensive emergency.
For some homeowners, the comparison is between an NFIP policy and private flood coverage. The best option is not always the lowest initial price. Compare the building and contents limits, deductible choices, waiting periods, exclusions, temporary living expense options, and whether coverage can be renewed on terms that work for the household.
Do Not Wait Until Rain Is in the Forecast
Flood policies often have a waiting period before coverage begins. A common NFIP waiting period is 30 days, although exceptions can apply in certain circumstances, such as some loan transactions or map revisions. Private flood insurance may have different waiting periods and rules.
That means flood coverage is a decision to make during calm weather, not when a storm is already approaching. Waiting until local streets begin to fill can leave a homeowner without protection for the event they are worried about.
It is also wise to create a simple home inventory before a loss. Take photos or video of each room, save receipts for major purchases when possible, and keep copies of your policy information where you can access them if the home is damaged. After a flood, photographs of water lines and damaged items can help support a claim, but safety comes first. Avoid standing water, damaged electrical systems, and structural areas that may be unsafe.
Questions to Ask Before Buying
A good flood insurance conversation should be specific to the property rather than based only on a map label. Ask whether the quote includes both the building and personal property. Ask what is excluded in a basement, garage, or enclosed area below an elevated home. Confirm the deductible, effective date, and whether temporary living expenses are available.
It also helps to review homeowners insurance and flood insurance together. You want to understand where one policy ends and the other begins, including coverage for wind-driven rain, water backup, and detached structures. If a storm causes more than one kind of damage, clear policy guidance can reduce confusion when it is time to report a claim.
A licensed agent can compare available options, explain policy language in plain terms, and help identify questions that a quick online quote may not address. At Hancy’s Insurance Agency, that means helping clients weigh price alongside coverage details and being available after the policy is in place.
The right time to understand flood coverage is before water reaches the doorstep. A short policy review now can give your household clearer choices, fewer surprises, and a better plan for protecting the place you call home.
Send the details once and let a licensed independent agency help you compare options.
Start a Quote